Fintech surge driving Ghana’s digital finance revolution — BoG Deputy Governor
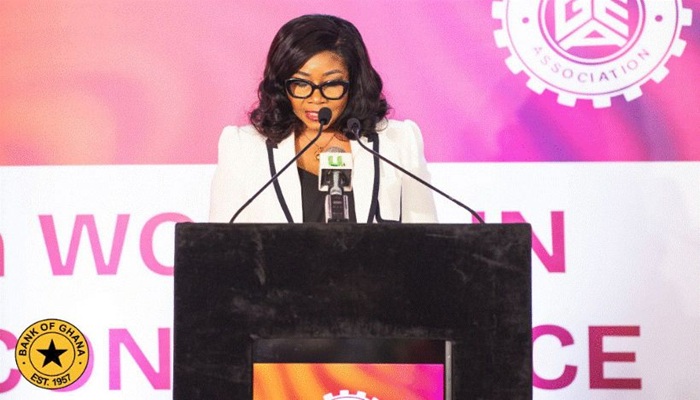
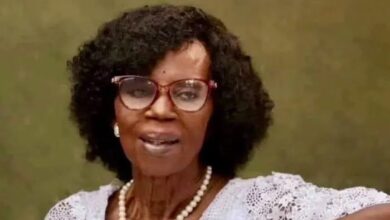
The Second Deputy Governor of the Bank of Ghana (BoG), Matilda Asante-Asiedu, has underscored the rapid expansion of the global and domestic fintech landscape, describing it as a powerful catalyst for financial inclusion and digital transformation.
Speaking at the MoMo Fintech Stakeholders Forum in Accra on Wednesday, 15 October, Mrs Asante-Asiedu revealed that the global fintech market is projected to reach USD400 billion by 2028, while digital lending alone has already surpassed USD1.3 trillion globally.
She noted that Ghana’s fintech industry continues to mirror this global trajectory, with innovations in mobile money, digital lending, and online payments reshaping how citizens transact, save, and access credit.
“The global fintech market is projected to reach USD400 billion by 2028, with digital lending alone surpassing USD1.3 trillion. This transformation is not just numerical but also cultural,” she said.
The Deputy Governor explained that fintech growth is redefining financial behaviour across societies, transforming the way people and businesses engage with money and financial institutions.
She emphasised that Ghana’s mobile money sector continues to experience strong growth, reflecting the country’s accelerating shift towards a digitally driven financial ecosystem.
“In Ghana, mobile money transactions continue to grow, highlighting the increasing reliance on digital channels for payments and transfers,” Mrs Asante-Asiedu stated.
She called for stronger collaboration between regulators, innovators, and service providers to sustain the industry’s growth momentum and safeguard financial stability.
Mrs Asante-Asiedu further reiterated the Bank of Ghana’s commitment to fostering an enabling regulatory environment that balances innovation with consumer protection and systemic resilience.
Her remarks come as the BoG intensifies its digital finance agenda, including the operationalisation of the Digital Credit Directive, the introduction of a virtual assets licensing framework, and nationwide efforts to promote financial literacy and consumer redress mechanisms.