BoG Losses Were Necessary for Economic Stabilisation

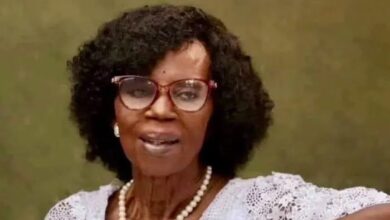
An economist at the University of Ghana, Dr. Gloria Afful-Mensah, has defended the financial losses recorded by the Bank of Ghana, arguing that they were necessary trade-offs that enabled macroeconomic stabilisation after the country’s recent economic crisis.
Speaking at a public forum in Accra, she stressed that the reported losses should not be interpreted as policy failure, but rather as “accounting and correctional costs” associated with restoring stability in a highly distressed economy.
“The losses that we are talking about are accounting losses and necessary correction losses,” she said.
Her comments come amid public debate over the central bank’s financial position following a period of aggressive policy intervention aimed at restoring confidence in the economy.
Dr. Afful-Mensah noted that Ghana’s stabilisation efforts must be understood against the backdrop of severe macroeconomic stress between 2022 and 2023, when inflation surged above 50 percent, eroding purchasing power, savings, and overall living standards. She explained that the Bank of Ghana’s response was anchored on its inflation-targeting framework, which seeks to keep inflation within a 8 ± 2 percent band.
“Currently the monetary policy that the Bank of Ghana is implementing is the inflation targeting framework and the framework thrives more on the ability to manage the expectations of the public,” she said.
She acknowledged, however, that structural weaknesses in the financial system continue to limit the effectiveness of monetary policy transmission. In particular, she pointed to the persistent rigidity in lending rates, which often fail to adjust in line with changes in the policy rate.
Her remarks align with broader assessments that the central bank played a critical stabilising role during the crisis period, absorbing shocks that might otherwise have destabilised the economy further.
Analysts note that the Bank of Ghana effectively functioned as a buffer institution, implementing extraordinary liquidity management measures to curb inflation and stabilise the Ghana cedi. These included large-scale open market operations, issuance of high-interest central bank instruments, and interventions in the foreign exchange market.
While these measures succeeded in sharply reducing inflationary pressures, they also generated significant financial costs. The Bank incurred recurring interest expenses on its own securities, while returns on corresponding assets lagged behind, contributing to balance sheet losses.
Additional interventions aimed at stabilising the currency and rebuilding reserves, including commodity-linked operations such as gold-based programmes, further exposed the central bank to non-traditional financial risks.
Despite these costs, Dr. Afful-Mensah argued that the overall outcome has been positive. Inflation has eased significantly to about 3.2 percent, growth is improving, and monetary conditions are gradually normalising. She also pointed to stronger confidence in the financial system and improved macroeconomic indicators as evidence of recovery.
She emphasised that the stabilisation process involved difficult trade-offs, but ultimately prevented more severe outcomes such as hyperinflation, a sharper currency collapse, and systemic banking sector distress.
In her view, the current economic gains reflect the effectiveness of the policy response, even if the accounting outcomes appear negative.
“The key issue is not the losses themselves, but what would have happened without those interventions,” she implied.
As Ghana continues its recovery phase, the debate over the cost of stabilisation versus the benefits of restored macroeconomic stability is likely to remain central in economic discussions.