Banking Sector Robust to Adverse Macroeconomic Developments – BoG
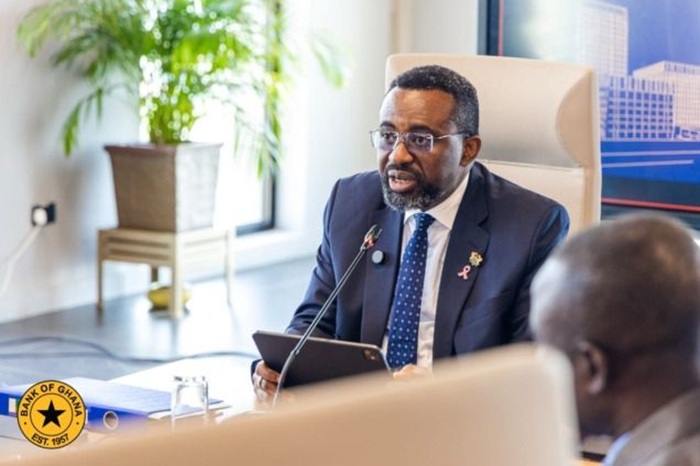
A stress test conducted in January 2026 by the Bank of Ghana (BoG) has revealed that Ghana’s banking sector remains robust even under adverse macroeconomic scenarios.
According to the Central Bank, the resilience of the industry is supported by strong capital buffers, improving macroeconomic conditions, and substantial holdings of government securities by banks, which continue to provide a stabilising cushion.
However, the BoG cautioned that a deterioration in macroeconomic conditions could negatively impact asset quality and increase operational costs. It noted, nonetheless, that such pressures would likely be partially offset by gains in net interest income.
Strong Asset Growth and Portfolio Rebalancing
The Central Bank observed that the banking sector’s performance in 2025 reaffirmed its resilience amid strengthening macro-financial conditions. Total assets expanded in December 2025 compared to December 2024, driven largely by higher deposit inflows and other funding sources.
The growth in assets was primarily attributed to increased investment holdings, reflecting what the BoG described as a cautious portfolio rebalancing strategy. Banks appear to be prioritising lower-risk government instruments over aggressive private sector lending, amid lingering credit risk concerns.
Improved Financial Soundness Indicators
Financial soundness indicators generally improved year-on-year, with the exception of core liquidity, which the Bank said requires close monitoring due to its potential implications for short-term funding stability.
The industry’s solvency position also strengthened. The Capital Adequacy Ratio (CAR), excluding regulatory reliefs, improved in December 2025 relative to the previous year. This was attributed to ongoing recapitalisation efforts across the sector as well as sustained profitability among banks.
Asset Quality Risks Remain
Although the Non-Performing Loans (NPL) ratio moderated during the review period, the BoG warned that asset quality concerns persist and remain an upside risk to the sector’s outlook.
The Central Bank concluded that the industry’s outlook remains stable, but this stability is contingent on the completion of recapitalisation by the end of March 2026 and the effective implementation of the BoG’s NPL regulatory guidelines aimed at strengthening credit risk management.
Overall, the stress test findings suggest that Ghana’s banking sector is better positioned to withstand external shocks than in previous years, supported by stronger capitalisation, improved profitability, and a more cautious risk posture.